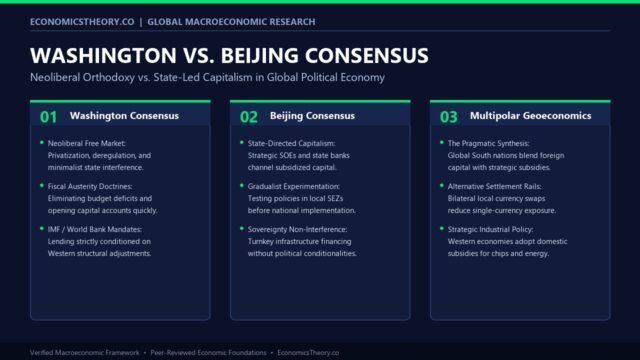
Executive Definition: The escalating geopolitical clash between De-Dollarization vs Dollar Dominance defines the primary faultline of the 21st-century international monetary system. While emerging economic coalitions (BRICS+) actively pursue de-dollarization—seeking to reduce reliance on the US dollar through non-dollar trade invoicing, gold accumulation, bilateral currency swaps, and central bank digital currencies—the structural institutional reality of dollar dominance persists. Supported by unparalleled US Treasury market liquidity, legal rule of law, the global Eurodollar wholesale banking network, and dominant trade invoicing standards, the dollar remains the undisputed linchpin of global finance.
1. The Structural Architecture of US Dollar Hegemony
Since the Bretton Woods conference of 1944, the US dollar has functioned as the primary global reserve currency. Novice market observers often assume that the dollar’s status is preserved solely by military might or historical habit. However, rigorous monetary economics reveals that the contest between De-Dollarization vs Dollar Dominance is governed by self-reinforcing network externalities and institutional balance-sheet mechanics.
In global macroeconomics, a currency’s international role operates across six distinct private and official functions, categorized by Paul Krugman and Jeffrey Frankel:
- Medium of Exchange (Private): Vehicle currency for foreign exchange transactions. According to the Bank for International Settlements (BIS) Triennial Central Bank Survey, the US dollar is on one side of roughly 88% to 90% of all global foreign exchange transactions.
- Medium of Exchange (Official): Central bank foreign exchange intervention medium. When central banks buy or sell currency to stabilize exchange rates, they trade US dollars.
- Unit of Account (Private): Trade invoicing and contract denomination. More than 54% of non-US global trade exports are invoiced in US dollars, far exceeding the United States’ actual share of global goods exports (~10%).
- Unit of Account (Official): Sovereign exchange rate anchor. Over 50 countries peg their currencies directly or loosely to the dollar.
- Store of Value (Private): Global banking and corporate liabilities. Over 65% of cross-border foreign-currency bank claims and international debt securities are denominated in US dollars (the Eurodollar market).
- Store of Value (Official): Central bank foreign exchange reserves. Sovereign treasuries hold dollars to guarantee national import coverage and liquidity defense.
2. Geopolitical Weaponization as a Catalyst for De-Dollarization
The contemporary de-dollarization movement was ignited into an urgent strategic priority following the unprecedented financial sanctions imposed by the G7 coalition in February 2022. Western authorities froze approximately $300 billion in Russian central bank foreign exchange reserves and expelled major Russian banking institutions from the Society for Worldwide Interbank Financial Telecommunication (SWIFT) messaging network.
For non-aligned sovereign nations—particularly China, India, Saudi Arabia, Brazil, and Indonesia—the freezing of sovereign central bank assets crossed a psychological threshold. It proved that dollar reserves held in Western custodians are not truly “risk-free” assets, but conditional liabilities subject to US foreign policy alignment. In response, sovereign central banks accelerated structural de-risking:
- Surging Physical Gold Accumulation: Central bank net gold purchases exceeded 1,000 metric tons annually in consecutive years, reaching historic highs as sovereign treasuries diversified into un-sanctionable, physical store-of-value assets.
- Local Currency Trade Settlements: Developing nations negotiated bilateral trade mechanisms denominated in local currencies, bypassing SWIFT and the New York clearing corridors (CHIPS).
3. Empirical Realities of Central Bank FX Reserves (IMF COFER Trends)
To evaluate whether the US dollar is undergoing rapid collapse or gradual erosion, economists track the International Monetary Fund’s Currency Composition of Official Foreign Exchange Reserves (COFER) data:
| Historical Milestone | US Dollar Share of Global FX Reserves | Euro Share | Chinese Renminbi (RMB) Share | Other Currencies (AUD, CAD, Gold) |
|---|---|---|---|---|
| Year 2000 (Peak Dollar Dominance) | ~71.5% | ~17.9% | 0.0% (Unallocated) | ~10.6% |
| Year 2010 (Post-Crisis Era) | ~62.2% | ~25.7% | 0.0% (Unallocated) | ~12.1% |
| Year 2024 (Present Structural Baseline) | ~58.4% | ~19.8% | ~2.3% | ~19.5% (Non-traditional reserves) |
The empirical data refutes apocalyptic claims of an imminent dollar crash. While the US dollar’s reserve share has drifted down from 71% to ~58% over a quarter-century, the lost share did not rotate into a rival geopolitical currency like the Chinese renminbi (which remains constrained near 2.3%). Instead, central banks diversified into non-traditional allied sovereign bonds: the Canadian dollar, Australian dollar, South Korean won, and physical gold.
4. Alternative Clearing Mechanisms: Bilateral Swaps, CIPS, and mBridge
Rather than seeking to create a single rival reserve currency, de-dollarization advocates are constructing parallel financial telecommunications and settlement architectures:
1. Bilateral Currency Swap Lines
The People’s Bank of China (PBOC) has established over 40 bilateral local-currency swap agreements totaling over 4 trillion yuan (~$570 billion) with central banks across Asia, Latin America, and the Middle East. These facilities allow trading partners to access yuan liquidity directly to settle imports without needing to purchase US dollars in foreign exchange markets.
2. The Cross-Border Interbank Payment System (CIPS)
Launched by China in 2015, CIPS provides independent clearing and settlement services for cross-border yuan transactions. While CIPS still relies on SWIFT messaging for many international transfers, it maintains a proprietary direct messaging capability that functions independently of Western financial infrastructure.
3. Project mBridge (Multi-CBDC Common Platform)
Developed jointly by the Bank for International Settlements (BIS) Innovation Hub, the People’s Bank of China, the Hong Kong Monetary Authority, the Bank of Thailand, and the Central Bank of the UAE, Project mBridge uses distributed ledger technology (blockchain) to settle cross-border wholesale transactions directly in central bank digital currencies. By enabling instant, atomic PvP (Payment-versus-Payment) settlement without routing through US correspondent banks, mBridge eliminates dollar intermediation and eliminates settlement risk.
5. The Petroyuan and Commodity Invoicing Transitions
Since the 1974 agreement between the United States and the Kingdom of Saudi Arabia, crude oil has been priced and settled exclusively in US dollars, establishing the structural demand foundation of the Petrodollar system.
Today, that exclusive arrangement is eroding. China, as the world’s largest crude oil importer, has initiated direct crude oil purchases from Russia, Iran, and Saudi Arabia settled in Chinese renminbi—the emerging Petroyuan. In 2018, China launched Shanghai crude oil futures contracts denominated in yuan with physical delivery convertibility into gold through the Shanghai Gold Exchange.
Similarly, India purchases discounted Russian Urals crude oil settled in UAE dirhams and Indian rupees, while Brazil and China settled agricultural trade (soybeans, iron ore) directly in local currencies. These shifts reduce the structural daily demand for dollar liquidity across international commodity corridors.
To explore how trade realignment shapes global economies, explore our dedicated research on Trade Realignment and Industrial Policy and review sovereign debt exposure in Global Sovereign Debt Overhang.
6. Comparative Matrix: The US Dollar vs Emerging Alternative Currencies
To evaluate whether any currency can displace the dollar, economists examine the prerequisites of global reserve status:
| Reserve Requirement | US Dollar (Current Hegemon) | Euro (Primary Competitor) | Chinese Renminbi (Strategic Challenger) |
|---|---|---|---|
| Sovereign Debt Market Depth | $27+ Trillion US Treasury market; deepest, most liquid capital market on Earth | Fragmented across German Bunds, French OATs, Italian BTPs; no unified federal debt safe asset | Growing domestic bond market, but heavily controlled by state-owned banks with limited foreign access |
| Capital Account Openness | 100% open; zero capital controls; free cross-border money flows | 100% open; free capital movement within EU and internationally | Closed / Managed capital account; strict quotas on currency conversion and foreign capital exits |
| Legal Protections & Rule of Law | Constitutional property rights; independent judiciary; contract sanctity | Independent European Court of Justice; robust legal protections | Judicial system subordinated to state policy; regulatory and expropriation risks |
| Willingness to Run Trade Deficits | High; persistent current account deficits supply dollar liquidity to the world | Low; structural export surpluses (Germany, Netherlands) drain euro liquidity from global markets | Zero; mercantilist export model generating massive current account surpluses |
7. The Triffin Dilemma and the Limits of Dollar Replacement
The ultimate barrier to replacing the US dollar lies in the Triffin Dilemma, formulated by Belgian-American economist Robert Triffin in 1960. The dilemma identifies an unavoidable structural contradiction facing any global reserve currency issuer:
To supply the world with sufficient foreign exchange reserves and trade liquidity, the reserve currency nation must run persistent balance of payments and trade deficits—spending more money abroad than it takes in. However, running perpetual trade deficits and accumulating massive sovereign debts over decades inevitably undermines the long-term credibility of the reserve currency.
Crucially, no other major economic power is willing or able to assume this burden. Neither China nor the European Union is willing to hollow out its domestic manufacturing export base, abandon capital controls, and run massive structural trade deficits to supply the world with liquidity. Until a credible alternative safe asset emerges, the international monetary system is transitioning not to a new single hegemon, but to a fragmented, multi-polar currency ecosystem where the US dollar remains the dominant primary reserve.
To understand the mechanics of central bank interest rate settings and liquidity facilities, review our complete guide on How Central Banks Use Interest Rates and study international spillovers in Global Interest Rates.
8. Frequently Asked Questions
Can the BRICS coalition create a single gold-backed currency to replace the US dollar?
A single common BRICS currency faces insurmountable structural hurdles. Member nations (China, India, Brazil, Russia, South Africa) possess wildly divergent trade balances, conflicting geopolitical interests, and vastly different capital account regulations. Establishing a shared currency requires a single unified central bank, shared fiscal backing, and coordinated macroeconomic governance, which member states are unwilling to surrender.
Why can China’s renminbi not become the dominant global reserve currency today?
Because China maintains strict capital controls that restrict the free movement of money in and out of the country. Foreign central banks and institutional investors will not store trillions of dollars in assets in a currency that cannot be freely converted, withdrawn, or liquidated during a financial crisis without state approval.
What constitutes the “exorbitant privilege” of the US dollar?
Coined by French Finance Minister Valéry Giscard d’Estaing in the 1960s, “exorbitant privilege” refers to the United States’ unique ability to borrow cheaply from the rest of the world in its own fiat currency. Because global central banks eagerly accumulate US Treasuries as reserves, the US can finance large fiscal and trade deficits at lower borrowing costs than other nations.
How does Project mBridge threaten Western financial surveillance?
Project mBridge enables commercial banks in participating nations to transfer digital central bank currencies directly over a decentralized ledger, bypassing both the SWIFT messaging network and Western correspondent banks. This makes transactions invisible to Western regulatory oversight, eliminating the leverage of unilateral dollar sanctions.
9. Primary Sources & Academic References
- Eichengreen, Barry. (2011). Exorbitant Privilege: The Rise and Fall of the East and West. Oxford: Oxford University Press.
- International Monetary Fund. (2023). Currency Composition of Official Foreign Exchange Reserves (COFER). Washington, DC: IMF Statistics Department.
- Bank for International Settlements. (2022). Project mBridge: Connecting Economies through CBDC. BIS Innovation Hub Report.
- Triffin, Robert. (1960). Gold and the Dollar Crisis: The Future of Convertibility. New Haven: Yale University Press.
- Krugman, Paul R. (1984). “The International Role of the Dollar: Theory and Prospect.” In Exchange Rate Theory and Practice (pp. 261–278). University of Chicago Press.
- National Bureau of Economic Research. (2023). Geopolitics and the International Monetary System. NBER Working Paper Series, No. 31405.